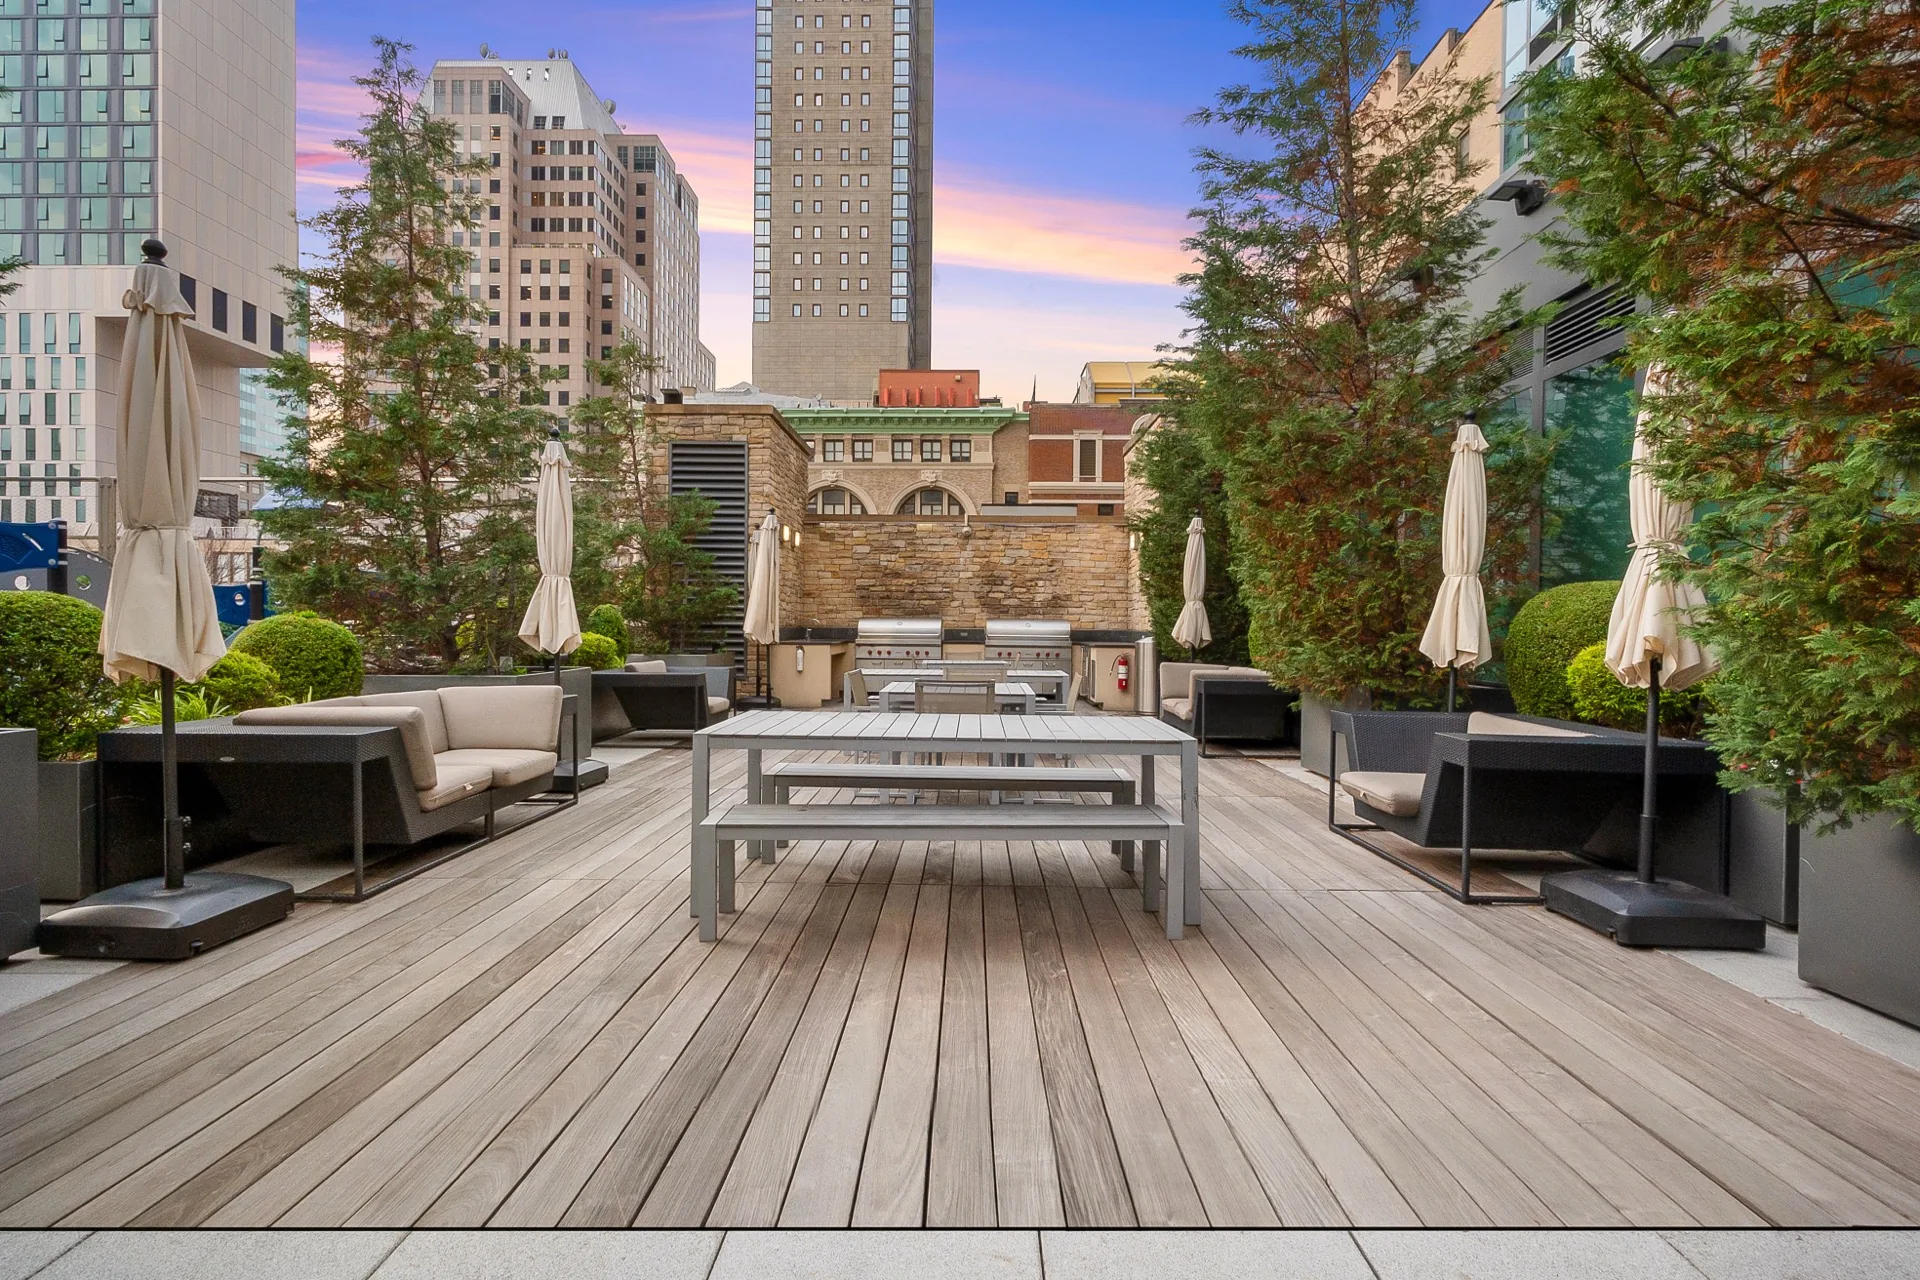
New development is the most heavily marketed corner of the New York City market and the least well understood. Buyers walk into a sales gallery, see a finished model unit, a rendering of a roof deck, and a glossy brochure — and sign a contract governed by a several-hundred-page legal document almost nobody reads.
That document is the offering plan, and it is the actual deal. Everything that matters lives there: what you are being sold, what the building will cost to run, what the sponsor may change without asking you, and what happens if construction runs two years late.
This guide is about the parts of a new development purchase that are not in the marketing materials — the projection that tends to run low, the concessions sponsors will make but rarely offer, and the diligence that separates a good buy from an expensive lesson.
What Counts as New Development
The term covers three genuinely different situations, and buyers frequently conflate them.
One
Ground-up new construction
A newly built condominium selling from an offering plan, often before completion.
Two
Conversion
An existing rental or commercial building converted to condominium ownership under a new plan.
Three
Legacy sponsor unit
An unsold apartment still held by the original sponsor in a building converted years or decades ago.
The third category is the one people miss. A sponsor unit in a 1985 co-op conversion is not new construction in any ordinary sense, but it carries several of the same consequences: you buy from the sponsor, you typically absorb the transfer taxes, and in a co-op you generally skip board approval entirely. That last point makes legacy sponsor units genuinely valuable to buyers who would struggle with a co-op board.
The Offering Plan Is the Contract
An offering plan is filed with the New York State Attorney General's Real Estate Finance Bureau before a sponsor may sell. It is a disclosure document, not an endorsement — the state reviews it for completeness of disclosure, not for whether the deal is good.
Renderings, floor plans in a brochure, and anything a sales associate tells you in the gallery are not binding. The plan is. When the two disagree, the plan governs, and buyers have discovered this the hard way over finishes, square footage, and amenities that appeared in marketing but never in the specifications.
Schedule A — the units
Every apartment in the building, with its projected common charges, real estate taxes, and percentage of common interest. Your common interest determines your share of every future assessment, so it matters well beyond closing.
Schedule B — the first-year budget
The sponsor's projection of what it will cost to run the building in year one. This is the single most consequential document in the plan and the one buyers read least carefully. See the section below.
Description of Property and Specifications
What you are actually being sold — appliance brands, finishes, systems, ceiling heights. Marketing renderings are not binding. This section is.
Rights and Obligations of Sponsor
What the sponsor may change without your consent, how long they control the board, their obligation to complete construction, and what happens if they do not.
The purchase agreement
The actual contract, printed in the plan. Unlike a resale, it is largely non-negotiable in its terms — but not entirely, and knowing which clauses sponsors will amend is a matter of experience.
Amendments
Filed over time as things change. Always ask for every amendment, not just the plan. A material change — construction delay, budget revision, design substitution — appears here, not in the original document.
Ask for the Amendments
Schedule B: The Projection Problem
Schedule B is the sponsor's projected first-year operating budget for the building. It produces the common charge figure printed on every listing sheet, and it is a projection — prepared on the sponsor's behalf, at a moment when low common charges make units easier to sell.
That incentive does not make Schedule B dishonest. It does mean the projection sits at the optimistic end of a reasonable range, and that a handful of line items are predictably where it runs thin: building staffing, insurance, utilities, and reserve fund contributions.
There is a second effect buyers rarely anticipate. While the sponsor still holds unsold units, they are paying common charges on them, and the building may be running with a lighter staff than it will eventually need. As the building sells out and residents take over the board, the real cost of operating the property asserts itself. Increases in the first few years after sellout are common enough that you should plan for one.
How to Pressure-Test the Number
Convert projected common charges to dollars per square foot per month
Compare against a similar, fully occupied building in the same neighborhood
If the projection is materially lower, ask specifically why
Ask whether staffing in the budget matches the amenities being advertised
Check the reserve contribution — an underfunded reserve becomes an assessment later
For an occupied building, ask for actual operating results, not the projection
A pool, a full-time doorman, a residents' lounge, and landscaped outdoor space cost real money to staff and maintain. If the projected charges look light relative to what is being promised, that gap does not disappear — it arrives later as a higher monthly bill or an assessment.
Who Controls the Board
In a new condominium the sponsor controls the board of managers until a threshold set out in the offering plan is reached — typically tied to the percentage of units sold, with an outside time limit. Until then, decisions about the budget, the managing agent, reserve funding, and construction acceptance are made by the party that built the building.
This is not inherently a problem, but it is a governance gap worth understanding. During sponsor control, the entity responsible for correcting construction defects is also the entity deciding whether construction defects exist. Buyers in early closings have limited practical recourse until residents take over.
Ask two questions before you sign: what percentage of units must close before control transfers, and how many have actually closed to date. A building that is 80% in contract but 30% closed is further from resident control than it sounds.
What You Pay That Resale Buyers Do Not
A new development closing costs meaningfully more than a resale at the same price — routinely $40,000 more on a $2 million purchase — almost entirely because the offering plan reassigns costs that a resale seller would bear.
NYC and NYS transfer taxes
Normally the seller's obligation. Most offering plans shift both to the buyer, adding roughly 1.825% of the purchase price on a sale above $500,000.
Sponsor's attorney fee
Commonly $2,000–$5,000, paid by you, on top of your own attorney.
Working capital contribution
Usually one to two months of common charges, non-refundable, funding the building's opening reserves. You are capitalizing the condominium, not prepaying your own charges.
Resident manager's unit contribution
Where the plan provides for a superintendent's apartment, buyers often fund a pro-rata share.
Mansion tax and mortgage recording tax
Unchanged from any condo purchase, and stacked on top of everything above.
Full figures, worked examples, and the resale comparison are in our NYC closing costs breakdown.
What Is Actually Negotiable
Buyers assume new development pricing is fixed. Pricing is the least flexible part — but the deal around it is often quite flexible, and understanding why explains what to ask for.
A sponsor resists cutting the headline price because the recorded sale becomes a comparable for every unsold unit in the building. It can also disturb appraisals for buyers already in contract. A $50,000 price cut on one unit can cost a sponsor far more than $50,000 across a sellout.
Concessions carry no such cost. They are invisible in the public record, they do not reset comps, and they can be granted unit by unit. This is why a sponsor who will not move $25,000 on price will sometimes absorb $36,500 in transfer taxes without much argument.
Transfer taxes
The most valuable single ask, worth roughly 1.825% of the price. Sponsors concede this more readily than any other item because it costs them less than an equivalent price reduction — and unlike a price cut, it never shows up in the public record.
Working capital and sponsor's legal fee
Smaller, but frequently waived, especially late in a sellout or on a unit that has lingered.
Common charge abatement
Six or twelve months of common charges covered by the sponsor. Attractive to sponsors because it is a defined, one-time cost that does not touch the recorded price.
Upgrades and credits
Appliance packages, finish upgrades, window treatments, or a flat closing credit. Easiest to obtain while the unit is still being built.
Storage, parking, or bike room
Where the building has them, these are separately priced amenities the sponsor can bundle at little marginal cost.
Closing timing
Rarely thought of as a concession, but a sponsor pushing to hit a lender's closing threshold may accommodate your timeline in exchange for certainty.
Where the Leverage Is
Closing on a Temporary Certificate of Occupancy
Most new development closings happen on a temporary certificate of occupancy rather than a permanent one. A TCO means your apartment and the necessary egress are legally habitable — it does not mean the building is finished.
In practice, early residents often move into a building where the lobby is incomplete, the gym has no equipment, the roof deck is fenced off, and construction crews share the elevators. This can persist for months. It is normal, it is legal, and it is rarely described in the sales gallery.
A TCO also expires and must be renewed. If a sponsor fails to renew or cannot obtain a permanent certificate, refinancing and resale both become complicated. Ask when the permanent certificate is expected and what the plan obligates the sponsor to do if it is delayed.
If You Are Buying to Live in It Immediately
Punch Lists and Warranties
Before closing you walk the unit and produce a punch list of items to be corrected — finishes, hardware, alignment, anything not built to specification. The sponsor's obligation to complete that list is defined by the offering plan, and the leverage you have to enforce it drops sharply the moment you close.
Take the walkthrough seriously. Bring someone who knows construction. Test everything that opens, closes, drains, or turns on. Photograph what you find and get the list acknowledged in writing rather than verbally.
Warranty coverage varies by plan and is frequently narrower than buyers assume. Do not rely on a general expectation that a new building comes with a warranty — have your attorney identify precisely what is covered, for how long, and who you contact when something fails after closing.
Tax Abatements and the Cliff
Many new developments carry a real estate tax abatement or exemption, and the monthly figure quoted to you often reflects the abated amount. Abatements are genuinely valuable. They also expire, usually by phasing out over a period of years rather than ending at once.
The risk is not the abatement. It is buying based on a monthly carrying cost that has a scheduled increase built into it, without understanding the schedule. A buyer who stretches to afford today's number may find the fully unabated figure uncomfortable — and every other owner faces the same increase at the same time, which is not ideal for resale values in that year.
Get the phase-out schedule in writing before you sign, and run your numbers against the fully unabated tax rather than the current one. If the deal only works at today's figure, it is worth knowing that before you are in it.
Two Numbers to Ask For
Delays and Your Deposit
Construction delays are the norm rather than the exception. A building projected to close in the spring may close the following winter, and buyers who sold a home or ended a lease around the original date can be left improvising for months.
New York law requires purchaser deposits under an offering plan to be held in escrow rather than spent by the sponsor on construction — a meaningful protection when your money may sit for a year or more. Your attorney should confirm the escrow terms and the conditions under which funds are released.
The plan will also state an outside date and describe your rights if the sponsor misses it. Those rights vary substantially from plan to plan. This is not boilerplate, and it is among the most important things your attorney reviews before you sign.
Practical Advice on Timing
Your Diligence Checklist
Work through this with your agent and attorney before you sign. Most of it takes a phone call, and each item has cost someone real money for not asking.
Read Schedule B against a comparable, fully occupied building — per square foot, not in total
Ask for actual operating results if the building has been occupied more than a year
Request every amendment to the offering plan, not just the plan itself
Confirm the percentage of units sold, and how many have actually closed
Ask who controls the board today and what threshold transfers control to residents
Confirm whether the sponsor is paying common charges on unsold units, and what happens when they sell
Get the tax abatement schedule in writing, including the phase-out years
Verify the projected real estate tax figure against the building's actual assessment
Ask your attorney to review the sponsor's construction completion obligations and outside date
Walk the actual unit, or the closest finished equivalent, before signing
Check the reserve fund contribution and whether it is adequate for the building's systems
Confirm what warranty, if any, the sponsor provides and for how long
We work extensively in Downtown Brooklyn new development — buildings like 11 Hoyt, Brooklyn Point, and The Brooklyn Tower — and can tell you how a specific building's plan, pricing, and concession history actually compare. See all buildings we cover.
FAQ: New Development in NYC
What is a sponsor unit in NYC?
A sponsor unit is an apartment being sold by the building's original owner or developer rather than by a previous resident. In a new condominium, every unit starts as a sponsor unit. In older co-ops and condos, a sponsor may still hold unsold apartments from the original conversion decades later. The common thread is that you are buying from the entity that filed the offering plan, which changes both the closing costs and the approval process.
Do I need board approval to buy new development?
No. There is no board package and no interview. The condominium board holds a right of first refusal, which is handled as an administrative waiver and is rarely exercised. This is a meaningful advantage over a co-op purchase, particularly for buyers using an LLC, buyers with non-traditional income, or international buyers.
Why do buyers pay the seller's transfer taxes in new development?
Because the offering plan says so. It is a term of the sponsor's purchase agreement rather than a legal requirement, which is precisely why it is negotiable. On a $2,000,000 purchase it is roughly $36,500 — the largest single concession most buyers can win.
Are projected common charges in the offering plan accurate?
They are projections prepared for the sponsor, and they are frequently optimistic. Staffing, insurance, and utility costs are the line items that most often come in above projection once residents control the board. Treat Schedule B as a floor rather than an estimate, and compare it per square foot against a comparable building that is already operating.
Can I back out if construction is delayed?
It depends entirely on the offering plan. Plans state an outside date for completion and describe your rights if the sponsor misses it, which may include rescission and return of your deposit. These provisions vary considerably, and this is one of the most important things for your attorney to review before you sign.
Is it better to buy early or late in a sellout?
They are different trades. Early buyers get the best selection of layouts, lines, and exposures, sometimes at introductory pricing. Late buyers get negotiating leverage, a building they can actually walk through, real operating history, and a common charge figure that is no longer hypothetical. If your priority is the specific apartment, buy early. If it is the deal, buy late.
What happens to my deposit before closing?
New York law requires purchaser deposits in a plan offering to be held in escrow rather than used by the sponsor for construction. Your attorney should confirm the escrow arrangements and the conditions for release, since this is the primary protection standing behind your money for what may be a multi-year period.
Final Thoughts
New development can be an excellent purchase. New systems, modern layouts, real amenities, no board interview, and in many buildings a tax abatement that materially lowers your carrying cost for years. None of that is marketing — it is genuinely why buyers choose it.
What the marketing does not do is prepare you to read Schedule B critically, ask who controls the board, or understand why a sponsor will hand you $36,500 in transfer taxes before moving $25,000 on price. Those are the things that separate buyers who negotiate well from buyers who simply pay the number on the price sheet.
The sales gallery works for the sponsor. Bring someone who works for you — Andreea Miller and Steven Markowicz read offering plans for a living — and have them read it before you fall in love with the model unit.
Disclaimer
Any figures in this guide are approximations. Offering plan terms, tax abatement schedules, common charges, and sponsor concessions vary building by building and change over time. Treat these as planning ranges, not quotes.
This is not legal or tax advice. The Miller Markowicz Team are licensed real estate professionals, not attorneys or accountants. Offering plans are complex legal documents and nothing here substitutes for review by your own attorney. Always confirm your specific situation with your own attorney and accountant.
Written by
The Miller Markowicz Team at The Corcoran Group
Andreea Miller and Steven Markowicz are licensed real estate agents at The Corcoran Group specializing in condos, co-ops, townhouses, and new development across Manhattan and Brooklyn — including Downtown Brooklyn, DUMBO, Williamsburg, Park Slope, Chelsea, and the Upper East Side.
Co-Founder · Licensed Associate Real Estate Broker
Recognized among The Corcoran Group's Top 25 agents and ranked in the top 1.5% of agents nationwide by RealTrends. Known for analytical rigor in pricing and a design-led approach to preparing and presenting homes.
Co-Founder · Licensed Real Estate Salesperson
A background in luxury hospitality shapes a client experience built on anticipation and responsiveness. Focused on Downtown Brooklyn, DUMBO, Williamsburg, and Boerum Hill, with deep new development experience.
Track Record
200+ transactions closed across Manhattan and Brooklyn
Top 25 at The Corcoran Group, five of the last six months
Top 1.5% of agents nationwide by RealTrends